Own the machine · Australia-wide
Buy an ATM for your venue — cut EFTPOS fees, get paid in cash
Card surcharges are being removed from 1 October 2026, so you can no longer pass card fees to your customers. An ATM in your venue turns cash back into your best-paid payment method: no merchant fees on cash sales, a cash discount you control, and ATM user-fee revenue that comes back to you.
Most enquiries receive a response within 3 hours during business hours.
What changed
The surcharge lever is gone — the card fees are not
From 1 October 2026, card payment surcharges are being removed in Australia. The Reserve Bank concluded it is in the public interest to remove surcharging by lifting its prohibition on the eftpos, Mastercard and Visa networks' no-surcharge rules, which lets those networks ban surcharges on their cards. A surcharge added because a customer pays by card falls under the change; discounts for paying cash are not affected.
The Payments System Board set the decision out in its March 2026 Conclusions Paper on merchant card payment costs and surcharging (RBA Conclusions Paper, Chapter 2), and announced it publicly on 31 March 2026 (RBA media release 2026-10). The RBA's own FAQ page confirms the start date of 1 October 2026 and that the changes only apply to card payment surcharges — weekend surcharges, public holiday surcharges and booking or service fees are untouched (RBA FAQ). We track each of these changes on our RBA card payment fee changes page.
Here is the part that matters for your margin: removing the surcharge does not remove your cost of accepting cards. The RBA expects payment costs to be folded into advertised prices instead — the same media release notes most consumers prefer costs built into the ticket price. You keep paying merchant service fees on every tap; you simply lose the ability to charge them to the customer. That is why venues are rethinking how much of their trade they want running through the card terminal at all.
The ATM answer
Tired of paying EFTPOS fees? Get paid in cash instead
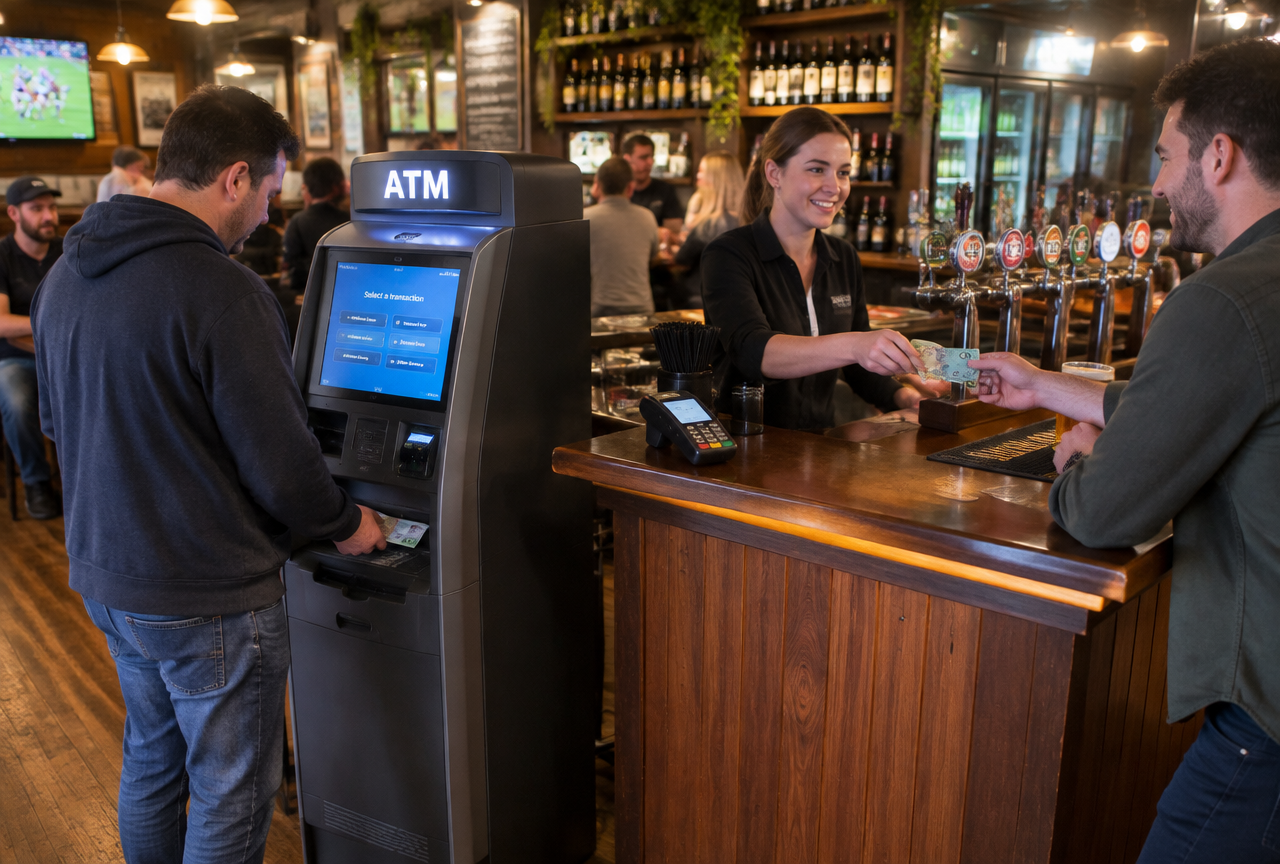
An ATM does not lower your card rates — it lowers how often you need them. Customers withdraw their own cash on site, then spend it at your counter.
No bank fees on cash sales
A cash sale carries no merchant service fee, no acquirer fee and no terminal rental per transaction. The card fees you pay only apply to the sales that stay on card.
Your customers get their cash on site
An ATM gives customers access to their own money inside your venue, and that money is what pays for your venue's services. No withdrawn cash walks out the door to the ATM down the street.
A cash discount you control
Discounts for paying cash are not affected by the surcharge changes. Pair the ATM with a simple cash price — the RBA points to discounts as the alternative to surcharging — and you generate demand for cash at your own counter.
The ATM pays you, not the other way
Every withdrawal carries a user fee. Under the ATMcash ownership model, approximately 84% of ATM user-fee revenue comes back to your venue — income that offsets the machine's capital cost, confirmed in writing with your quote.
Side by side
A card sale versus a cash sale through your own ATM
The same $100 of trade, taken two ways, in a venue that owns its ATM.
| What happens | Customer pays by card | Customer pays cash from your ATM |
|---|---|---|
| Who pays to process it | You — merchant service fee, scheme fees, terminal rental | Nobody at your end — no merchant or acquirer fee on the sale |
| The withdrawal itself | Not applicable | Cardholder pays the ATM user fee; roughly 84% of that revenue returns to your venue |
| Pricing at the counter | One price only — surcharges are being removed from 1 October 2026 | You may offer a cash discount — unaffected by the surcharge changes |
| Settlement | Funds batch to your account next business day, after fees | Cash is in your drawer immediately, already counted by the machine |
| Your exposure | Card fees scale with every sale, and interchange and scheme fees keep moving | Cash has fixed handling costs — float, banking and staff time — set up once |
We are not going to tell you cash is free — the float ties up working capital, someone has to bank it, and staff time costs money. But those costs are largely fixed once a system is set up, while card fees charge you per sale forever and the RBA's reforms show how quickly the rules around them can move. Every percentage point of trade you shift from card to cash is a percentage point that stops compounding on your merchant statement.
The numbers
What an owned ATM actually earns
Owning the machine means the user-fee revenue is yours. The two variables are your foot traffic and how much of it wants cash.
Pubs, clubs and late-trade venues are the clearest case: customers want cash for the bar, the tab and the gaming room, and they will pay a user fee to get it on site. Busy 24-hour, highway and late-trade sites commonly recover a refurbished machine inside 6–12 months of surcharge income. Quieter sites are usually better served by free placement with an agreed revenue share, or a lease, and we will tell you straight if the numbers favour that for your site.
Under the ATMcash ownership model, approximately 84% of ATM user-fee revenue comes back to the venue — the figure that pays for the machine's capital cost over its life. Your exact return depends on withdrawal volume and transaction mix, so we confirm the split in writing with your quote. To model it yourself, put your machine price and weekly withdrawals into the ROI calculator on our buy-an-ATM page and it will show monthly income and payback in months.
- Delivery and professional installation Australia-wide
- Staff training on loading, balancing and reconciliation
- Tap & Go kit so customers can withdraw with their phone or card
- Ongoing technical support and parts from day one
- A written ownership split — the percentage of user-fee revenue that comes to you
Contact us
Find out how an ATM pays your venue
Tell us your venue type, trading hours and rough weekly foot traffic. We will come back with the right machine, the installed price, the ownership split and what it should earn — and an honest comparison against free placement if that suits your site better.
What happens after you hit send
- 1You get an instant email confirming we've received your enquiry.
- 2We check your venue type, hours and foot traffic against the right ATM option.
- 3You get a call or email with a clear recommendation and pricing — your choice which.
Reply within 3 business hours
A real person reviews every enquiry. Mon–Fri 8:30am – 7:30pm AEST · Online enquiries 24/7, most venues hear back the same morning or afternoon.
Your details stay private
Sent over an encrypted connection, stored securely, and never sold or shared with third-party marketers.
No obligation, no pressure
You get honest advice on whether free placement, a lease or buying suits your site — walk away any time.
Prefer to talk it through first? Call 0412 025 552
Answers
Buying an ATM to cut EFTPOS fees — FAQs
Surcharging on the designated card networks (eftpos, Mastercard and Visa) is being removed from 1 October 2026. The Reserve Bank has lifted its prohibition on the networks' no-surcharge rules, which allows the networks to ban surcharging on their cards. Check the RBA's FAQ page and your payment provider for the exact timing that applies to your terminal.
Yes. The RBA's changes target card payment surcharges — an extra fee added because a customer pays by card. They do not stop a business from offering a discount for a particular payment method, and the RBA itself points to discounts as the alternative to surcharging. We have a plain-English guide to offering a discount for cash, including how to display it.
An ATM does not change your terminal rates — it reduces how often they are used. Customers withdraw cash on site, then spend that cash at your counter. Each cash sale carries no merchant service fee and no card acquirer fee, so the fee-paying share of your takings falls. The cash also stays in your drawer, which many venues bank less often than card settlements arrive.
Yes. Every withdrawal pays the cardholder a user fee (the ATM surcharge), and when you own the machine that fee revenue is yours rather than an operator's. Under the ATMcash ownership model, approximately 84% of ATM user-fee revenue comes back to the venue. The exact figure for your site depends on withdrawal volume and transaction mix, and we confirm it in writing with your quote. Put your own numbers through the ROI calculator on our buy-an-ATM page.
Cash has real costs — the float, banking, counting and staff time — and we will not pretend otherwise. The difference is how those costs behave: card fees charge you per sale, forever, and that charge is rising as interchange and scheme fees change. Cash handling is largely fixed once a system is set up. For most venues with an ATM on site, cash also arrives already counted in the machine's balancing records.
Refurbished ATMs start from $4,500 including the Tap & Go kit, with new and through-the-wall machines quoted per site. Delivery, installation, staff training on loading and balancing, and ongoing technical support are included. If buying does not suit your volume, free placement and lease options are compared on the same page.
You supply and manage the float by default, which is why you keep the surcharge revenue. We train your staff on loading, balancing and reconciliation at installation, and we can quote managed cash loading if you would rather not touch it. Technical support and parts are covered from day one.
No. This page is general information about payment costs and ATM ownership, prepared from publicly available Reserve Bank of Australia publications. It is not financial, legal or taxation advice. Confirm the surcharging changes with the original RBA sources and your own advisers before making decisions.
EFTPOS fees
Still weighing up the card side?
If you want the card terminal costs checked at the same time, we compare EFTPOS machine fees, terminal rental and merchant rates off one recent statement. Compare EFTPOS machine fees or ask about both in the same enquiry.
- Compare EFTPOS machine fees AustraliaSend one recent merchant statement and see your real all-in cost per transaction.
- Buy an ATM, cut EFTPOS feesCard surcharges end 1 October 2026. Own the ATM, take cash sales without merchant fees and earn a share of every withdrawal.
- Zero-cost EFTPOS & surchargingHow compliant customer surcharging shifts the terminal cost off your margin.
- Convenience store EFTPOS feesLow-basket, high-tap sites often pay more in fixed fees than percentage rates.
- Petrol & service station EFTPOS feesFuel card mix, pay-at-pump volumes and per-transaction pricing reviewed together.
Related
More on payment costs and cash access
- Offering a discount for cash — how to price a cash discount now that surcharges are ending.
- ATM revenue and profit share — how user-fee revenue is split between venue and operator.
- ATM for venues — placement options by venue type, free or owned.
- Free ATM placement FAQ — the zero-cost option, if buying does not suit your volume.
Ready to stop paying to take payments?
Send your venue details or call 0412 025 552 — Mon–Fri 8:30am – 7:30pm AEST · Online enquiries 24/7.
Disclaimer: this page is general information only, prepared from publicly available Reserve Bank of Australia publications and ATMcash's own offer terms. It is not financial, legal or taxation advice. Card surcharging rules and timetables can change — verify the detail with the original RBA sources, your payment provider and your own advisers before making decisions. Earnings figures depend on withdrawal volume and transaction mix and are confirmed in writing with your quote.